Alimony vs. Child Support: How Each Fits Your Post-Divorce Budget
Alimony and child support may both arrive as monthly payments and appear in the same divorce agreement. In your real budget, however, they are not the same kind of money.
They serve different purposes, may follow different rules, and may change or end on different timelines. Treating them as one permanent monthly number can create trouble when you plan housing, childcare, work, or the years after support changes.
This distinction can feel emotionally loaded. If you stepped away from work to care for your family or your spouse managed the finances, asking for support may trigger guilt or shame. You may hear one person say, “Take everything you can get,” while another warns you never to depend on support.
Between those extremes is a more useful question: What can you realistically afford, and how does each payment fit into the plan?
Receiving support does not mean you failed to become independent. A support order also does not replace a complete financial plan.
Child Support Is Intended to Help Meet Children's Needs
Child support is intended to help meet the needs of the children. That may include everyday costs such as housing, food, clothing, school needs, transportation, healthcare, childcare, and other expenses connected to raising them.
The calculation and what is included can vary by state and family situation. Your attorney should explain the rules that apply to your case.
Emotionally, it helps to remember that child support is not a personal favor to the receiving parent. Children affect far more than the grocery bill. They affect the size and location of the home, transportation, work schedules, childcare needs, and the flexibility required when something unexpected happens.
Minimizing those costs to appear agreeable may leave the household without a realistic plan. Understanding them accurately is not the same as being demanding.
The Monthly Child-Support Amount Is Only One Question
A single number may not explain which expenses are covered separately or how parents are expected to handle costs that do not arrive every month.
Ask:
What expenses are included in the stated amount?
Who pays health insurance premiums for the children?
How are uninsured medical expenses divided?
Who pays for childcare?
How are school fees, activities, tutoring, special needs, or extraordinary expenses handled?
What records are required for reimbursement?
How and when should reimbursement requests be made?
Vague agreements invite different assumptions. Specific language can create clearer expectations and a better foundation for the household budget.
Alimony Supports a Spouse Under Applicable Law
Alimony may also be called spousal support or maintenance, depending on the jurisdiction. Unlike child support, it is intended to provide support to a spouse or former spouse under circumstances recognized by state law.
It may be temporary during the divorce, continue for a defined period afterward, or be structured differently according to the facts and applicable law. Amount and duration may be influenced by factors such as the length of the marriage, income differences, earning capacity, age and health, time away from the workforce, education or training needs, and the marital standard of living.
There is no single outcome that applies to every person in every state. A friend's agreement, a relative's experience, or an online story may have involved different facts and different rules.
Ask your attorney how your state's law and your actual circumstances shape the conversation. General examples can help you find questions, but they cannot determine your result.
Unpaid Labor and Career Sacrifices Still Matter
Many women contributed to a marriage in ways that never appeared on a pay stub. They raised children, managed a home, supported a spouse's career, moved for another person's opportunity, or paused their own earning growth because the family needed them elsewhere.
Those contributions were real even when no paycheck arrived every two weeks.
Recognizing that history does not guarantee a specific support award. It does mean you do not need to approach the conversation as though needing a transition period proves weakness.
Ask for a clear explanation of the proposed amount, duration, purpose, and assumptions. You can plan for increasing independence while also evaluating support that may be appropriate under the law.
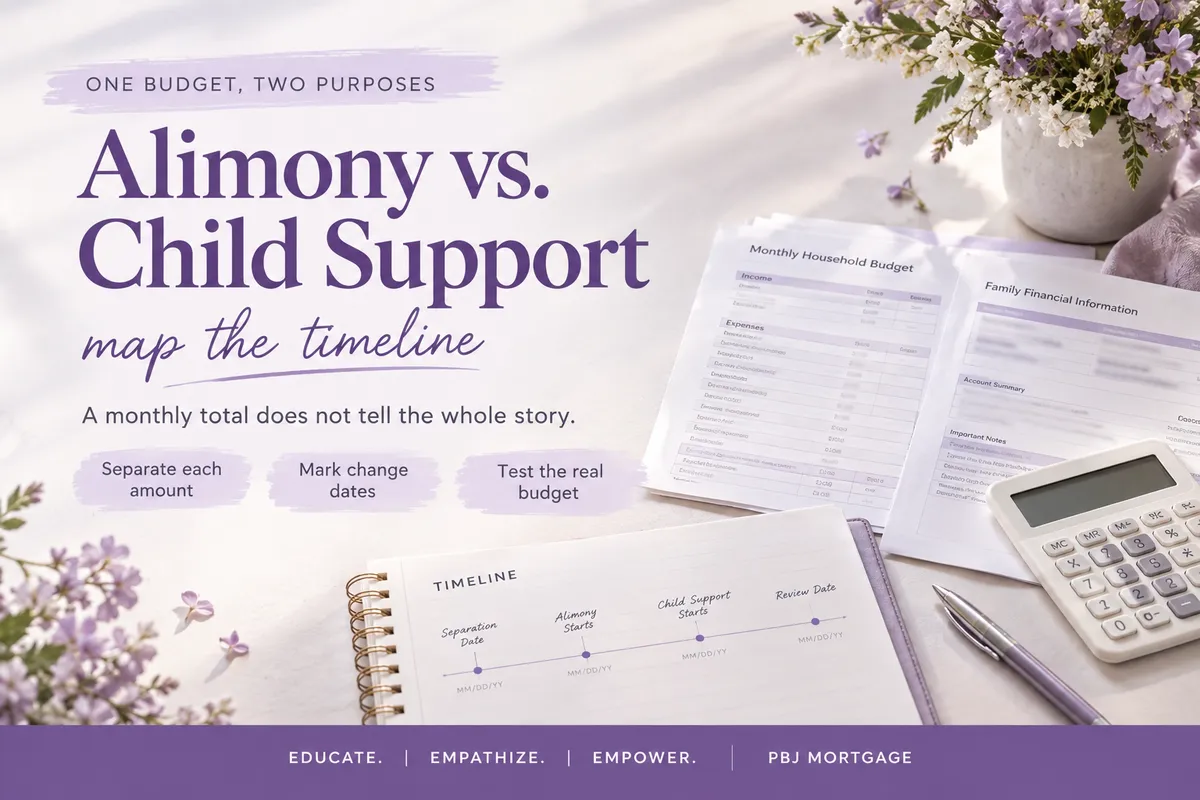
Build a Timeline, Not Just a Total
A combined monthly number may feel reassuring until you learn that one portion changes or ends earlier than the other.
Child support may change when a child reaches a certain age or another legal event occurs. Alimony may end after a defined period or change under circumstances described in the agreement or state law. One payment may stop years before the other.
A budget that works today may not work at the next transition point.
Ask when each payment begins, when it can change, when it is scheduled to end, what events may trigger review or modification, how payments will be documented, and what process applies if a payment is late.
Also ask what may happen if the paying spouse loses a job, retires, or stops cooperating. You cannot forecast every event, but you can mark the known transitions and avoid treating the current total as permanent.
Tax Treatment Can Depend on Dates and Jurisdiction
People often repeat tax information from a divorce that happened years ago. Under current federal rules, child support is not taxable income to the recipient and is not deductible by the payer.
For many divorce or separation agreements executed after 2018, alimony is also generally not included in the recipient's federal taxable income and is not deductible by the payer. Older agreements and certain modifications may be treated differently, and state tax rules may also matter.
Have a qualified tax professional review your specific agreement rather than relying on another person's experience. The amount received is not the only number that affects your financial life. Housing, insurance, childcare, debt, and other obligations all shape what remains.
Support Income and Mortgage Qualification Require Documentation
If you hope to refinance the marital home or buy another property, you may wonder whether alimony or child support can be considered as income.
Lenders may evaluate support based on documentation, consistency, expected continuation, and applicable underwriting requirements. A proposed sentence in a draft agreement may not be treated the same as an established payment history.
Speak with a qualified mortgage professional before the settlement is finalized whenever possible. The mortgage professional does not decide the support arrangement or provide legal advice. The conversation can help you understand what documentation and timing may matter to the housing plan.
You may learn that refinancing appears possible, that a later purchase could be more realistic, or that renting temporarily offers useful flexibility. None of those paths should be promised in advance. They should be explored using income that can actually be documented and relied upon.
Let Support Be a Bridge With a Visible End
A common fear is, “What if I depend on support and then it stops?” That concern deserves planning, not automatic rejection of support you may need or be entitled to receive.
A longer-term stability plan may include:
Creating a realistic household budget
Returning to work gradually when appropriate
Completing education or training
Building emergency savings
Reducing debt
Planning for known payment changes
Aligning housing costs with the next phase, not only the first year
Support can function as a bridge. A bridge works best when you understand where it begins, where it may end, and what you are building on the other side.
Plan for Late or Missed Payments
A court order matters, but your monthly cash flow matters too. If support arrives inconsistently, repeated private promises may not be enough to protect the household budget.
Keep payment records. Use formal payment channels when available. Document partial or missed payments, and speak with your attorney or the appropriate court or child-support agency about enforcement options in your state.
Do not wait until several months of expenses have collapsed before asking what can be done. Whenever possible, avoid a housing payment that leaves no room for a delay or unexpected expense.
This is not a prediction that the other parent or spouse will fail to pay. It is a recognition that a workable plan needs both legal protection and practical breathing room.
Do Not Trade Support Without Comparing What Replaces It
You may consider accepting less support in order to keep the house, or giving up another asset because monthly support appears sufficient. Those pieces are not interchangeable without analysis.
A house carries taxes, insurance, maintenance, and repairs. An asset may grow over time. Support may have an end date or depend on events described in the agreement.
Ask your attorney to explain the legal trade. Involve a financial or tax professional when appropriate. If housing is part of the decision, ask a mortgage professional whether the financing and monthly costs appear realistic.
Different professionals see different consequences. Those consequences eventually meet inside one household budget, so the conversations should not stay isolated.
Test the Budget at Each Known Support Change
A useful budget does more than show whether the first month works. Create a second version for the next known change: when one support payment is scheduled to end, when childcare changes, or when another event described in the agreement may alter income.
Then ask what would need to be different by that date. Would employment income need to grow? Could debt be lower? Would the housing cost still be manageable? How much emergency savings would create breathing room?
You are not trying to predict every detail. You are giving a future transition enough visibility that it does not arrive as a complete surprise.
If the plan depends on several optimistic events happening at once, ask what a more conservative version would look like. A workable first year matters, and so does the year after a major payment changes.
Support and Independence Can Exist in the Same Plan
It can feel as though accepting support means admitting that you cannot build independence. That is a false choice.
A transition plan can recognize the economic reality of the marriage while also identifying the work, education, savings, debt reduction, and housing steps that may strengthen your future. The specific pace will depend on your health, caregiving responsibilities, employment opportunities, and other circumstances.
Support does not have to be a vague promise of permanent security. It can be one documented part of a broader plan whose dates, risks, and next steps you understand.
Create a Support Worksheet You Can Actually Use
Write down:
The proposed child-support amount
The proposed alimony amount
The start and expected end date for each
Known events that may change either payment
Expenses assigned separately
Insurance responsibilities
Tax questions
The process for delayed or missed payments
Then compare the timeline with actual expenses: housing, utilities, food, transportation, childcare, medical costs, debt, and the irregular costs that appear throughout the year.
Review at least the first few known transition points, not only the first month after divorce. That is how a legal number becomes a living plan.
Clarity Creates More Stability Than Shame
You do not need to minimize your children's needs to appear agreeable. You do not need to feel ashamed for asking what spousal support means. You also do not need to build a future around assumptions that no one has explained.
Child support helps meet children's needs. Alimony may support a former spouse under applicable law. Both belong within the complete picture of income, expenses, timing, documentation, and future independence.
If you want help understanding how documented support may affect a mortgage, refinance, or future home purchase, PBJ Mortgage is here for a private, no-pressure strategy conversation. We can explain the mortgage side while your attorney and tax professional address the legal and tax questions.
Educate. Empathize. Empower.
A monthly payment is not the whole plan. Clear information helps you build the rest.
