When Your Ex Won’t Sell or Refinance the House After Divorce
Your divorce agreement says the house must be sold or refinanced. The deadline approaches—or passes—and your former spouse keeps delaying.
Paperwork goes unfinished. Lender requests are missed. Every proposed realtor or offer is rejected. “Next week” becomes next month while your name may remain attached to the mortgage.
If you moved out and believed the agreement ended the financial connection, the situation can feel both unfair and frightening. Your credit may still be exposed, the outstanding loan may still affect future financing, and a house you no longer control may continue shaping your options.
Legally ending a marriage and financially separating a mortgage are not always the same event.
Whether the delay is caused by refusal, emotion, poor communication, or an actual qualification problem, promises alone will not create a release. You need verified loan information, clear legal guidance, and a realistic next step.
Ownership and Mortgage Responsibility Are Different
Title generally relates to ownership of the property. The mortgage relates to responsibility for the loan. Changing one does not automatically change the other.
You may sign away ownership rights and remain responsible for the mortgage if the lender has not released you. A divorce agreement may award the home to your former spouse and require that person to make the payments, but the lender may still consider you a borrower while your name remains on the loan.
That means a late payment or default may still affect you. The outstanding obligation may still appear when you apply for other financing.
Sending a decree to the lender does not automatically rewrite the loan contract. The court governs the agreement between spouses; the lender governs the mortgage. A workable strategy needs to address both.
“Refinance When Able” Is Not a Complete Plan
Refinancing generally means that the spouse keeping the home obtains a new loan or another lender-approved solution that removes the other spouse's responsibility. It may not be possible immediately.
Income may be insufficient. Credit or debt may create a barrier. Interest rates may make the new payment unaffordable. The appraisal may not support the needed financing. Support documentation or other lender requirements may take time.
Depending on the loan and lender, an assumption or another type of release may sometimes be worth exploring. Do not assume refinancing is the only possible conversation, and do not assume a lender will remove a borrower simply because the settlement requests it.
Ask the servicer or a qualified mortgage professional what options may exist for that specific loan. Begin early, before an agreement creates a deadline that the financing process may not realistically meet.
If Your Former Spouse Is Delaying, Move From Texts to Documentation
It is easy to become trapped in an exhausting loop of reminders, polite requests, new excuses, and renewed hope. Your financial protection should not depend on endless informal conversations.
Gather and preserve:
The divorce order or settlement
Current mortgage statements and payment history
Emails and written requests
Lender correspondence
Refinance applications, updates, or denials
Realtor communications
A record of deadlines and missed deadlines
Then ask your divorce attorney about enforcement options in your state. The proper legal response depends on the wording of the order, the facts, and applicable law. A threat copied from social media is not a substitute for advice about your case.
A Sale Provision Needs Operational Details
“The parties will sell the home” leaves many opportunities for conflict. Before signing, ask how the sale will actually happen.
Which realtor will be used and how will that person be selected?
When must the property be listed?
How will the initial price be chosen?
When and how will the price be adjusted if offers do not come?
Who approves and pays for repairs?
Who pays the mortgage, taxes, insurance, utilities, and maintenance while the home is listed?
How will offers be evaluated?
What happens if someone refuses to sign closing documents?
How will net proceeds be divided?
Your attorney determines what language is legally appropriate. Your role is to understand the practical steps behind the language. In a high-conflict relationship, every undefined decision can become another delay.
Refusal May Be Emotional—or It May Be Leverage
The house may represent the children, the marriage, status, control, or the belief that selling means losing. Emotional attachment can be genuine.
It still does not justify leaving the other spouse financially attached indefinitely.
In some situations, the house may become leverage: a reason you must keep responding, a way to limit your future financing, or another obstacle to moving forward. If the pattern goes beyond ordinary communication problems, stop treating it as something you must solve through better reminders.
Bring in appropriate support. That may include your attorney, a realtor experienced with divorce-related sales, a mortgage professional or servicer, and—if payments are at risk—housing-counseling or foreclosure-prevention resources.
If You Are the One Who Cannot Refinance, Face the Barrier Early
You may be the spouse who wants to keep the home and cannot qualify by the deadline. That does not automatically mean you were dishonest or irresponsible.
Qualification can be affected by income, credit, debt, interest rates, support documentation, and property value. Ignoring the deadline will not change those factors.
Start early. Ask what is preventing approval, whether the issue may realistically be corrected, how long that could take, and what alternative the agreement provides. Discuss the situation with your attorney before the deadline passes.
Depending on the facts, a defined extension, another lender-approved path, or a sale may need to be considered. The answer may be painful. A clear answer is still safer than pretending the problem is not there.
Protecting the Children Does Not Always Mean Keeping One Address
Worrying about disruption is understandable. Children may love the house, school, neighborhood, and routines you are trying to preserve.
Children also feel ongoing financial tension and conflict. They notice the anxiety of a parent whose credit and future remain tied to an unstable situation.
Keeping one address at any cost is not the only definition of stability. Stability may mean a smaller home with predictable payments, a sale before missed payments damage the equity, or a clean financial separation that allows both parents to move forward.
The most familiar option is not automatically the most sustainable one.
If a Mortgage Payment Is Missed, Treat Time as Important
Do not wait quietly after learning that a payment has been missed. Confirm the loan status, review your credit reports, contact the mortgage servicer, and ask what information or options may be available. Speak with your attorney about the agreement and the missed obligation.
If foreclosure is a concern, contact the servicer and a HUD-approved housing counselor as soon as possible. The appropriate response depends on the loan and situation, but delays can narrow options.
Do not rely only on what your former spouse says about the account. Verify the status directly when you are entitled to do so.
Verification is not dramatic. It is a way to protect credit, equity, and future housing possibilities.
Use the Right Professional for Each Part of the Problem
No single person controls every piece of a delayed house plan. Your divorce attorney can explain the order, possible enforcement, and what language may be appropriate. The mortgage servicer or a qualified mortgage professional can explain the requirements and possible loan paths.
A real estate professional familiar with divorce-related sales can help translate a sale requirement into listing, pricing, showing, repair, offer, and closing decisions. If missed payments create possible foreclosure risk, a HUD-approved housing counselor may offer additional guidance.
Ask each person to stay within the role they know. A lender cannot rewrite the divorce order, and a legal deadline cannot make a borrower qualify. Coordination helps you see where the legal plan and the financing reality do—or do not—fit.
Clear Requirements Protect Both Spouses
A detailed timeline may sound distrustful while negotiations are calm. In practice, it can reduce future arguments by giving both people the same expectations.
Defined documents, deadlines, proof of progress, expense responsibility, and a backup sale path can answer questions before stress turns them into conflict. They also create a way to distinguish a genuine lender delay from a refusal to act.
Not every contingency can be predicted, and your attorney will determine what can be included. The value of detail is not punishment. It is making the process understandable when cooperation becomes harder than everyone hoped.
Build a Deadline and a Backup Path Before Signing
A more complete house plan may need to identify:
The refinance, assumption, or other approved-release deadline
The documents each spouse must provide
How progress and completion will be verified
Who pays property expenses during the transition
What happens if the lender denies the request
When the home must be listed as a backup
How the sale process will be managed
What happens if a person refuses to cooperate
A legal deadline without a realistic financing path can create another crisis. A financing hope without a legal backup can create endless delay. Ask your attorney and mortgage professional to help you understand both pieces before you agree.
If the Delay Has Lasted Months or Years, You Can Still Begin
You are not foolish because you believed the agreement would be followed. You may have wanted to avoid conflict, protect the children, or trust that the lender would remove your name automatically. Emotional exhaustion may have made one more fight feel impossible.
Time passing does not require you to keep waiting without a plan.
Understand How the Existing Mortgage May Follow You
Even when your former spouse makes every payment on time, the mortgage may still appear as an obligation when you explore another home. How a future lender evaluates it can depend on the loan, the payment history, available documentation, and applicable underwriting requirements.
Do not build a new-housing plan around the assumption that the divorce decree makes the mortgage invisible. Bring the agreement, recent statements, and available payment history to a qualified mortgage professional. Ask what may need to be documented and how the unresolved loan could affect timing or purchasing power.
The answer may show that another option is possible, or that waiting until the old mortgage is resolved would be safer. Neither answer is a promise. Both can help you avoid committing to a housing timeline that does not fit the financial reality.
Your attorney can address the former spouse's obligations. The mortgage review can help you understand the practical impact while the obligation remains.
Gather the order, loan records, and written communications.
Confirm the current mortgage and payment status.
Review the deadlines and obligations in the agreement.
Ask the servicer or mortgage professional what may be possible.
Speak with your attorney about the next appropriate, enforceable step.
One document, one phone call, and one professional conversation at a time can move the situation out of indefinite delay.
The House Should Not Keep You Financially Married
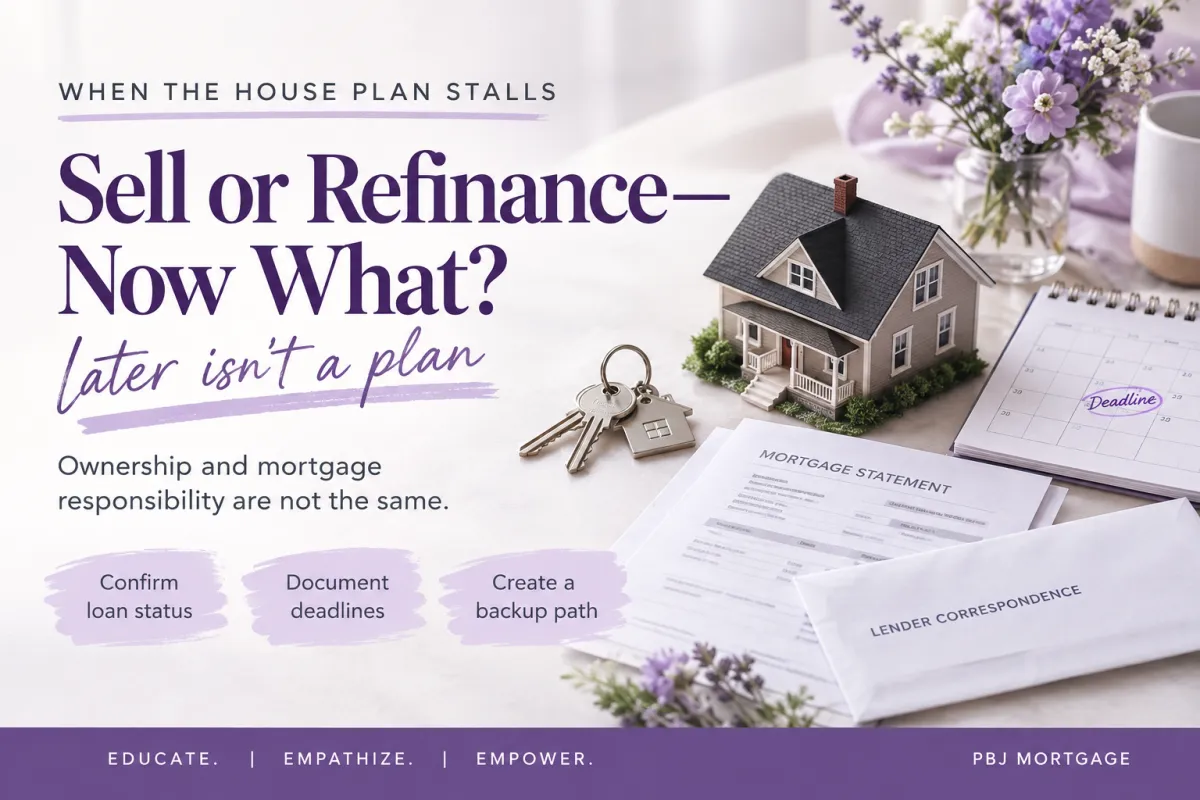
Ownership is not the same as mortgage responsibility. A promise is not a lender release, and “later” is not a dependable timeline.
You are allowed to ask for action, verification, deadlines, and a backup plan. Those requests are not hostile. They recognize that your credit and future housing options may still be connected to the loan.
If you want help understanding how the existing mortgage may affect a refinance or your ability to purchase another home, PBJ Mortgage is here for a private, no-pressure strategy conversation. We can help you explore the mortgage options and questions while your attorney guides enforcement and legal language.
Educate. Empathize. Empower.
You do not have to remain financially trapped by a house you no longer control.
