Divorce & your home

What happens to your mortgage in a divorce?

Keeping the house. Refinancing. Starting somewhere new. You deserve to understand what each option means for your life—and your finances.

We help you work through the mortgage questions before important decisions are finalized. Start with where you are. You don’t need every answer today.

A conversation about your situation. Room for your questions.

Jacqueline “Jax” Crider seated in an armchair
Real people. Clear guidance.Jacqueline “Jax” CriderManaging Partner · NMLS #943284Meet Jax and the PBJ team

Start with this distinction

The house and the mortgage are two different decisions.

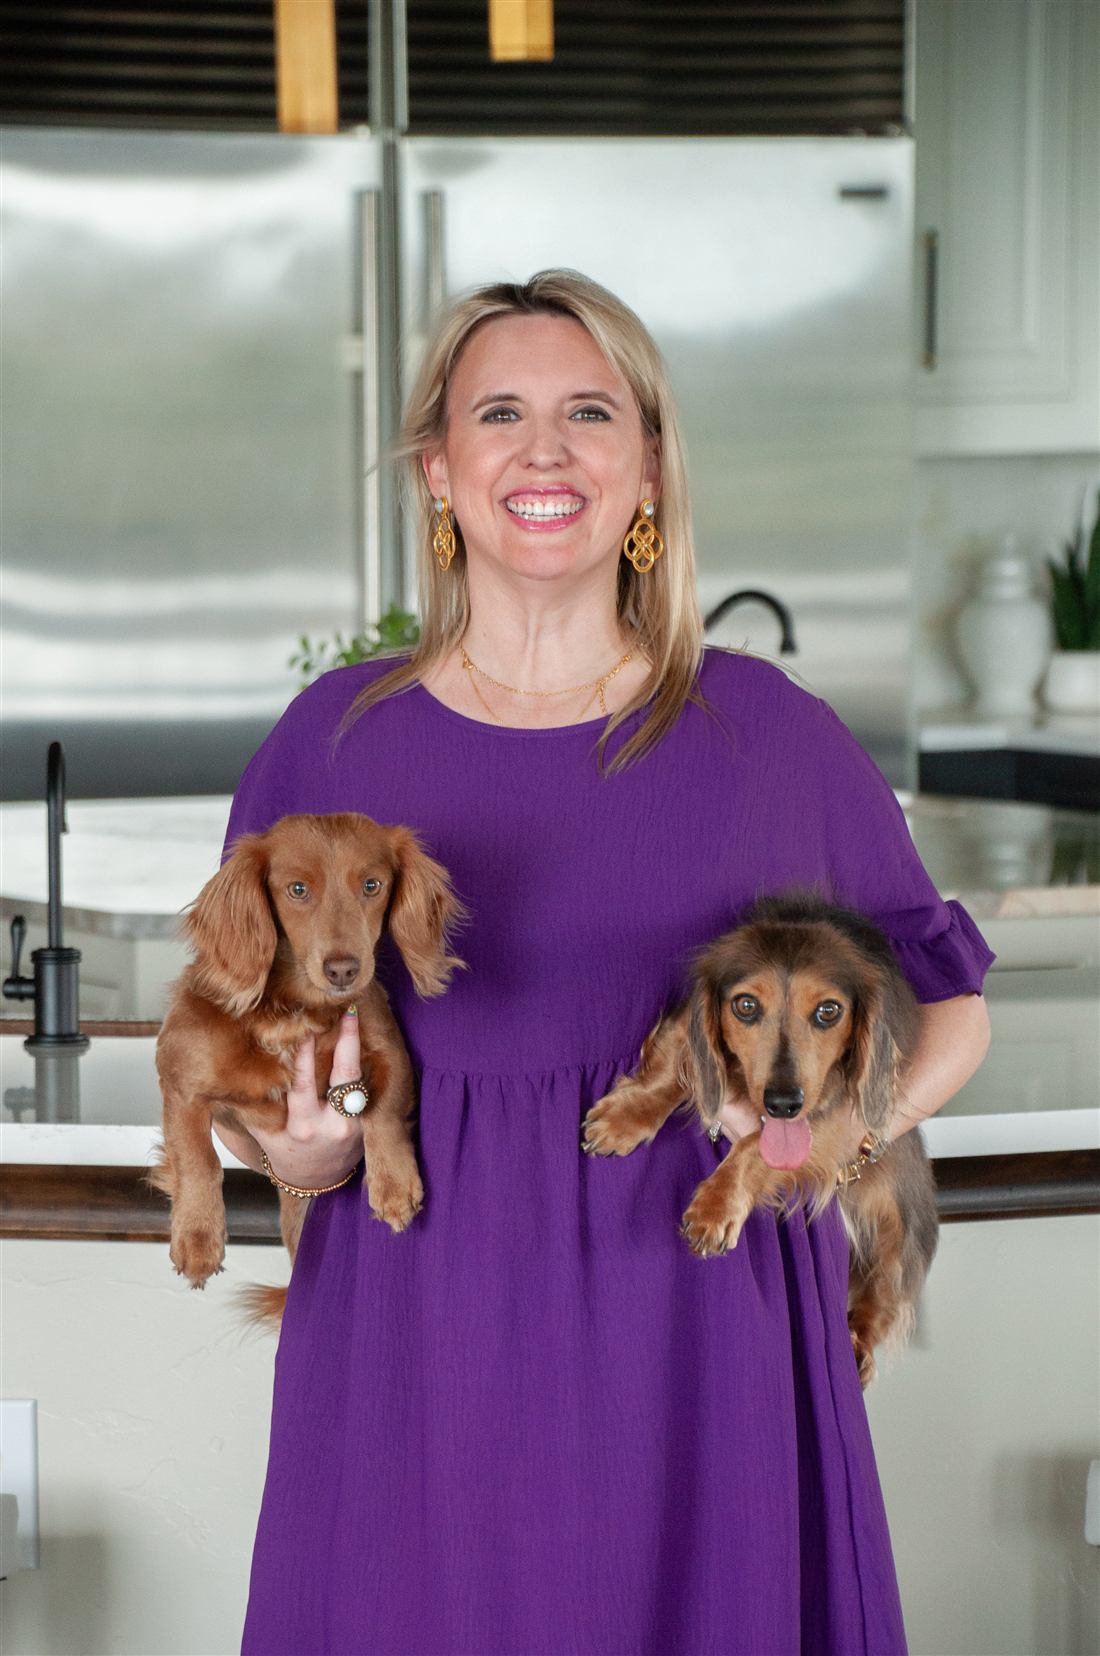
Jax Crider holding Peanut Butter and Jelly in a kitchen.

A divorce agreement can say who keeps the home. It does not, by itself, release a borrower from the mortgage.

Ownership

Ownership is about the property’s title.

Mortgage responsibility

Mortgage responsibility is about the loan agreement.

Removing a name from the deed does not automatically remove it from the debt.

The financing and the legal agreement need to work together.

Source: CFPB guidance on debt after divorce. Ask your attorney how your agreement applies to your circumstances.

A decision that fits your next chapter

Keeping the house is one option.
Let’s look at the others, too.

Start with the path closest to what you’re considering. Each has its own questions to resolve.

Illustrative housing photo: reviewing a contract beside a model house.

Keep the home and refinance

A new mortgage may pay off the existing loan and, where the structure allows, help fund an equity buyout.

Qualification and the new payment need to work for the person staying.

Look beyond the rate

Review cash to close, the full monthly cost, remaining savings, and the settlement’s timing.

Build the full housing picture
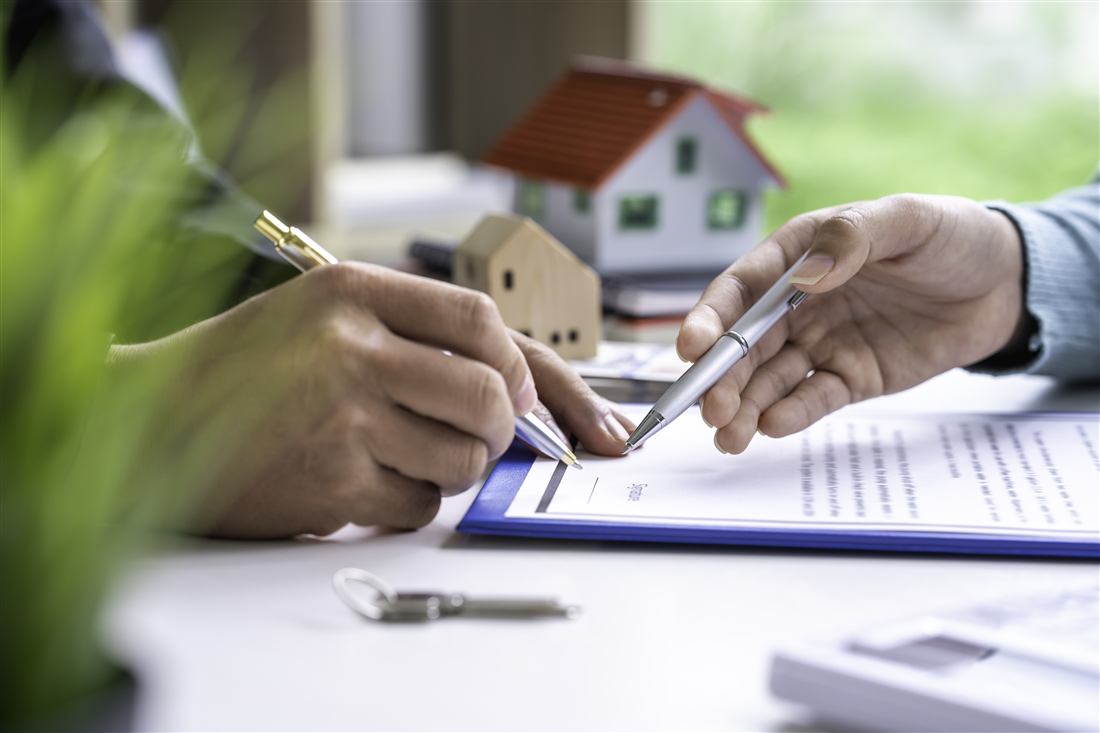
Illustrative housing photo: reviewing home-purchase paperwork.

Ask about the existing loan

An eligible ownership transfer, an assumption, and a release of liability are different things.

Ask the current servicer which procedures apply before assuming a refinance is your only route.

Get the details in writing

Ask about documentation, review requirements, fees, timing, and whether the departing borrower would be released.

Read the CFPB’s explanation
Illustrative housing photo: a woman holding a for-sale sign outside a house.

Sell and plan your next home

Selling can turn equity into resources for your next chapter.

Compare likely net proceeds and moving costs with the cost of renting or buying somewhere else.

Give yourself room to decide

Buying again immediately is not the only next step. Consider how each path affects cash flow and flexibility.

Explore renting as a reset

Options depend on the loan, servicer, borrower, property, and settlement. A property transfer does not guarantee an assumption or a release of liability. PBJ does not control your current servicer’s decision.

Affordability comes first

Can the home support the life you’re building?

Illustrative housing photo: keys held above a model home.

A mortgage payment is only part of what a home costs. Put the full monthly picture beside the income you can realistically rely on—and the savings you want to keep.

Read: Should you keep the house after divorce?

Your housing picture

Mortgage
Principal and interest
Property costs
Taxes, insurance, HOA dues
Everyday costs
Utilities and upkeep
Room for the unexpected
Repairs and emergency savings

Then ask: What’s left for everything else?

Before the agreement is final

Bring the mortgage questions into the conversation early.

Jax Crider seated in a purple dress.

A housing plan is stronger when the financing, settlement terms, and day-to-day budget are considered together.

  1. Understand what’s there

    Gather the mortgage statement, estimated home value, any other liens, and the costs of keeping the property.

  2. Test the financing

    Review income, debts, credit, available assets, and potential payments. Ask which facts or documents could change the answer.

  3. Coordinate the next step

    Take the financing questions back to your attorney and other advisers before agreeing to a deadline or buyout you may not be able to complete.

Will support income count?

Possibly, if you want it considered and it meets the selected program’s requirements.

Written terms, payment history and expected continuation matter. A promised payment and income a lender can use are different things.

You do not have to disclose alimony or child support income unless you want it considered for qualification.

See Fannie Mae’s current requirements

Make the next conversation useful

A few questions worth bringing with you.

Jax Crider standing in a blue blouse in a kitchen.

You can start talking before you have every document. These questions help identify what needs a closer look.

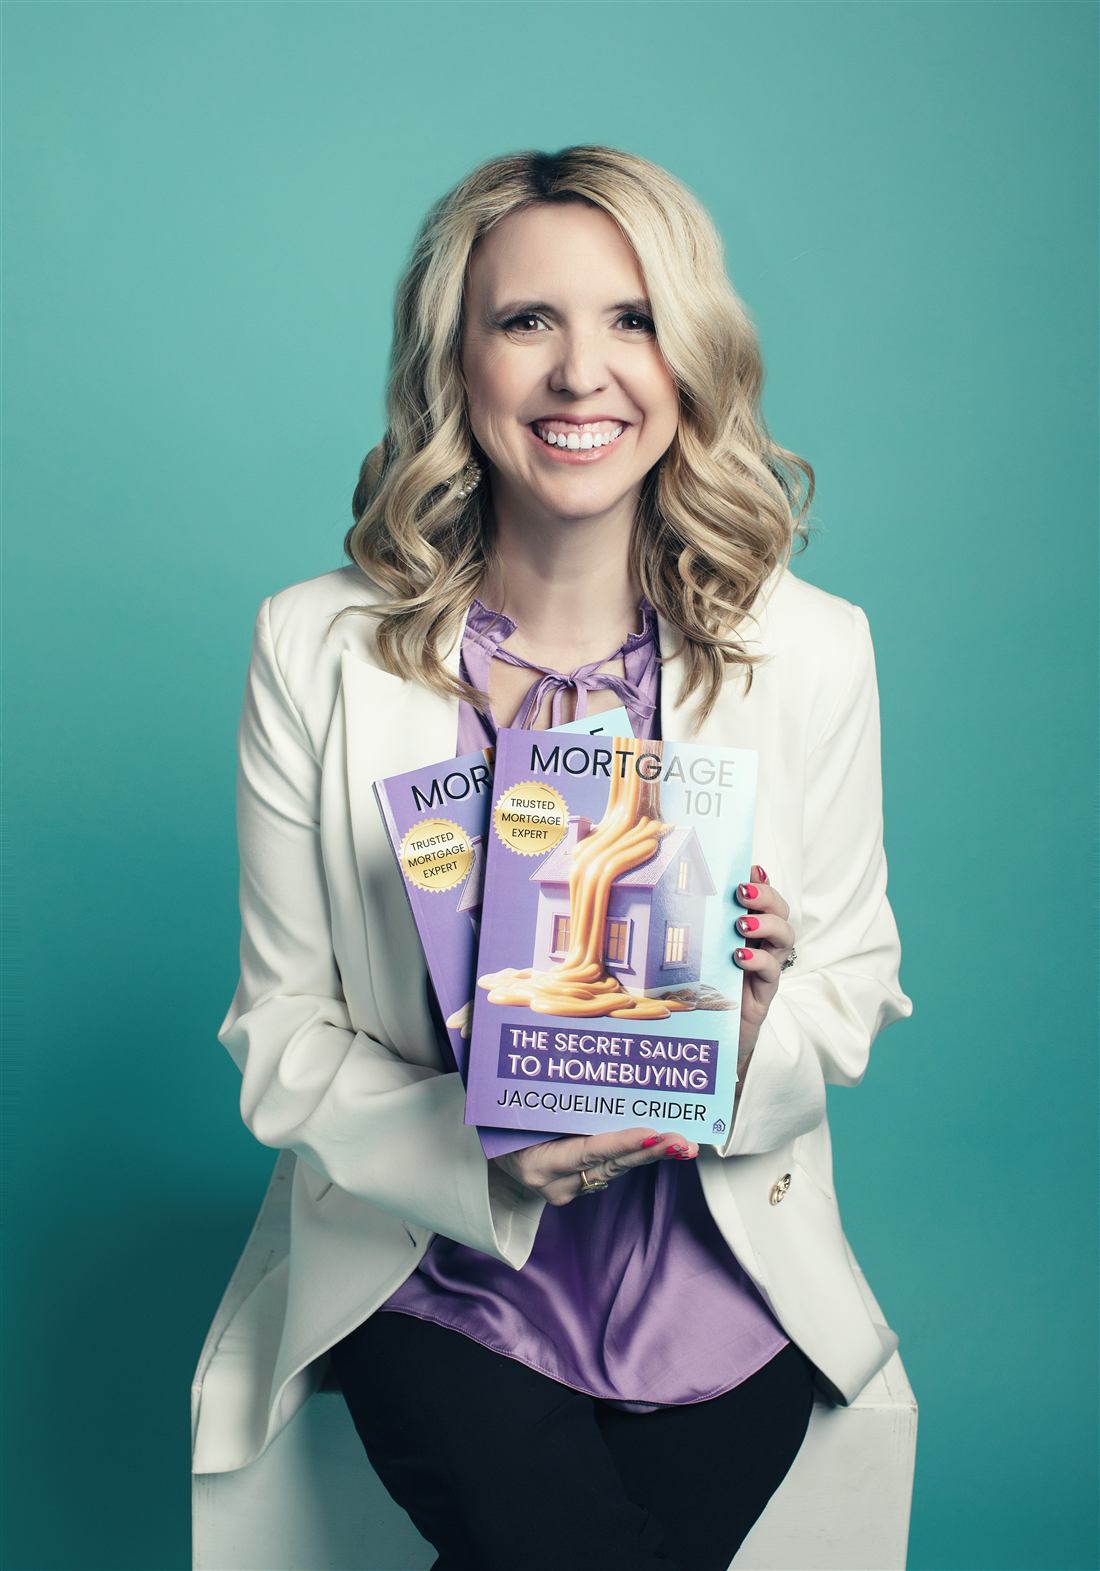
If the mortgage language feels unfamiliar, start with Mortgage 101: The Secret Sauce to Homebuying.

Save the conversation checklist
  • What is the current mortgage balance, and are there other liens?
  • What would I need to qualify for the option I’m considering?
  • How would an equity buyout affect the payment and my savings?
  • What should I ask the servicer about an assumption or release?
  • Which deadlines should my attorney and mortgage team discuss?
  • What happens if the first financing plan does not work?

Educate. Empathize. Empower.

Mortgage guidance, with space for the human side.

Jax Crider holding Peanut Butter and Jelly in a bedroom.

PBJ Mortgage is based in McKinney, Texas. Jacqueline “Jax” Crider and the team help you understand the financing questions so you can discuss your housing decisions with greater clarity.

We can work alongside your attorney and financial professionals on the mortgage side of the plan. Legal, tax, and settlement decisions belong with the appropriate advisers.

Get to know the people behind PBJ

Get to know the person behind the guidance: read Jax’s profile at Urals.

Listen to Financial Mastery Simplified: Can You Keep Your House After Divorce? Know Your Options. In Jax’s separate educational podcast, explore the questions behind keeping a home and planning your next step.

Questions we can work through

You’re allowed to ask the practical questions.

Jacqueline “Jax” Crider holding copies of Mortgage 101: The Secret Sauce to Homebuying.

Start here, then bring the details of your loan and settlement to a conversation.

Does the divorce decree take my name off the mortgage?

No. A decree can assign responsibility between spouses, but it does not by itself release a borrower from the loan agreement. Confirm how a release or payoff would be completed with the lender or servicer and your attorney.

CFPB: debt after divorce
Do I have to refinance to keep the house?

Not in every situation. The existing loan, ownership transfer, and whether someone needs a release of liability affect the available procedures. Ask the servicer to explain the applicable options before making a financing commitment.

CFPB: servicing after divorce
Can I use alimony or child support to qualify?

It may be possible if you choose to have it considered and it meets the selected program’s requirements. Payment history, written terms, expected duration, and supporting documentation matter. Requirements vary; a payment promised in a settlement is not automatically qualifying income.

Read how alimony and child support fit your post-divorce budget.

Fannie Mae: support-income requirements
What happens if I can't refinance after divorce?

If you cannot qualify for a refinance, the divorce agreement does not, by itself, release a borrower from the existing mortgage. Identify the barrier with a mortgage professional and discuss the deadline and a backup plan with your attorney. A different timeline, a lender-approved alternative, or selling may need to be considered; none is automatic.

Read what to do when a refinance or sale stalls after divorce
Should I speak with a mortgage professional before mediation?

Early financing information can help you bring practical questions to mediation: potential payments, documentation needs, equity funding, and timing. Your attorney advises on the agreement; the mortgage conversation helps test its financing assumptions.

Can You Buy a House Before Your Divorce Is Final? What to Check Before You Sign

Can You Buy a House Before Your Divorce Is Final? What to Check Before You Sign

Can you buy a home before your divorce is final? Learn how mortgages, marital property, joint debt and timing can affect your options before you sign. ...more

Divorce

November 13, 2026

Will My Ex's Mortgage Count Against Me When I Buy a House After Divorce?

Will My Ex's Mortgage Count Against Me When I Buy a House After Divorce?

A divorce decree may help exclude an old joint mortgage from debt-to-income calculations, but it does not remove your loan liability. Learn the difference. ...more

Divorce

November 11, 2026

When Monday Morning Feels Like an Escape From Your Marriage

When Monday morning feels like relief from conflict at home, understanding your mortgage options during divorce can help you make informed decisions about the family home. ...more

Divorce

November 02, 2026

From our Google reviews

Clear explanations make a difference.

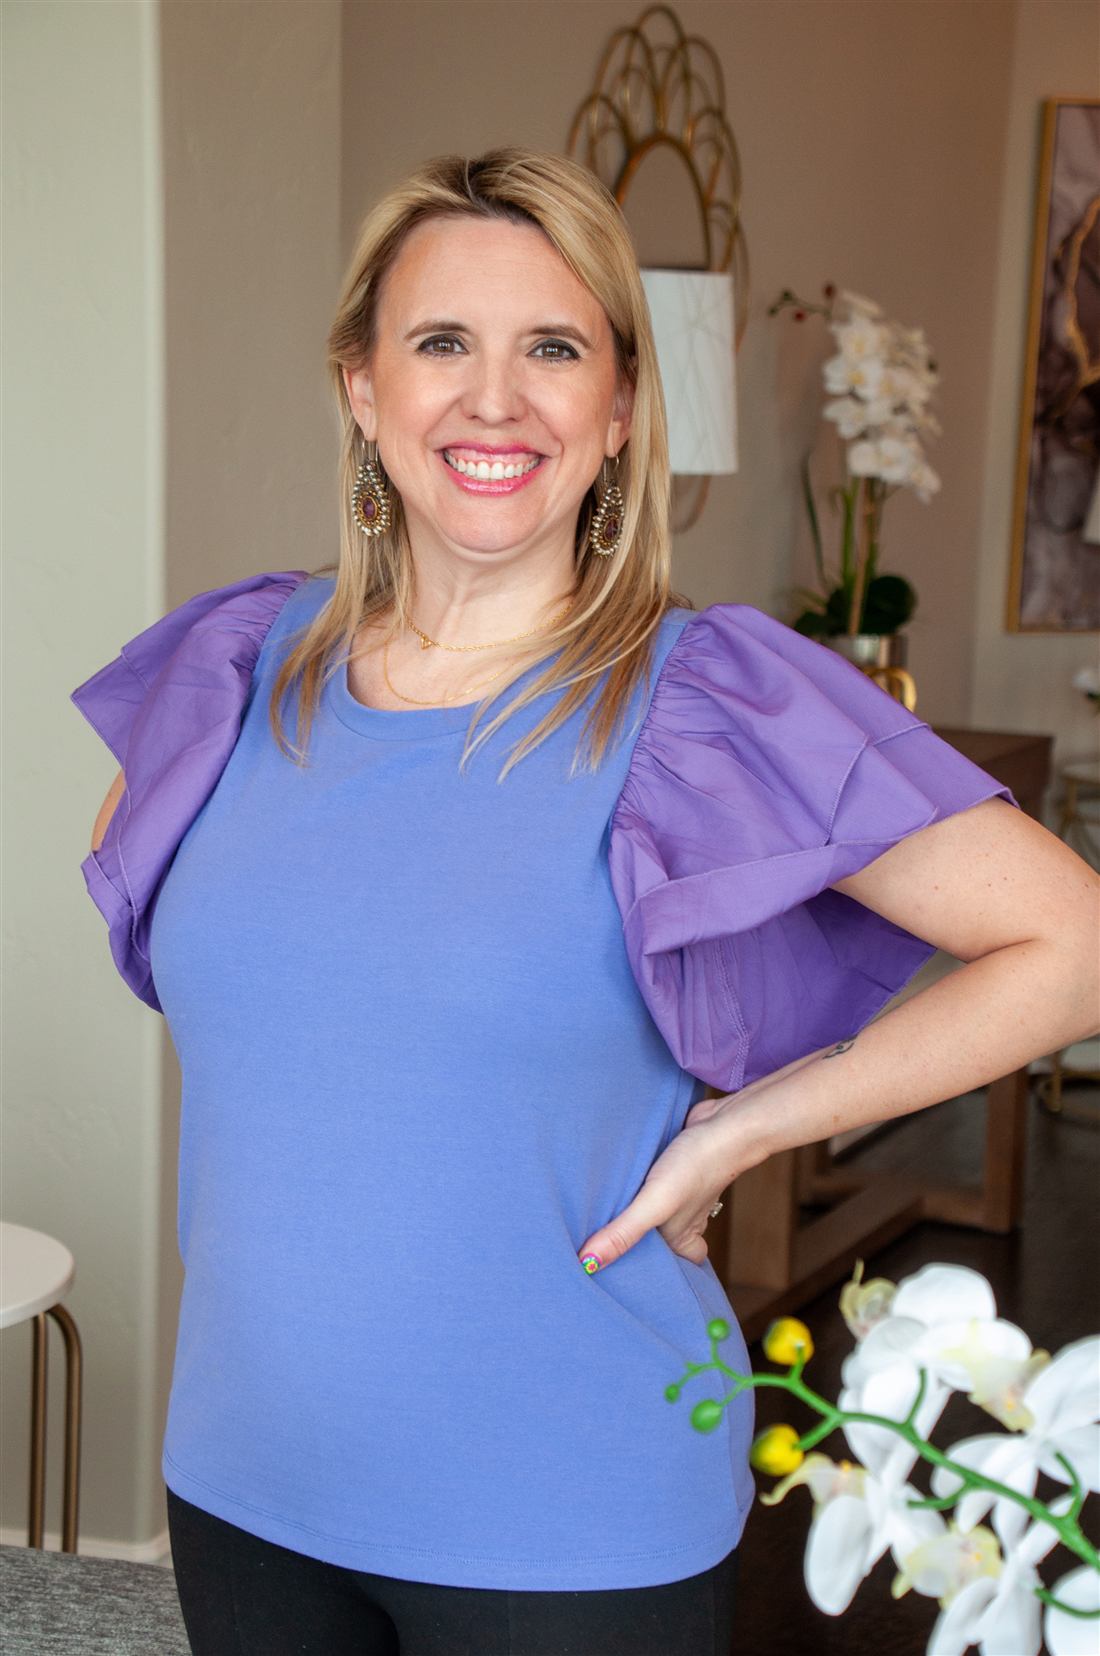
Jax Crider in a purple blouse at home.

“I learned so much from Mrs. Crider! She is truly the best in her field and it shows. Highly recommend!”

Heather Marie · Google review

View the PBJ Mortgage Google profile. Individual experiences vary.

Your next step can be a conversation

You don’t have to figure this out alone.

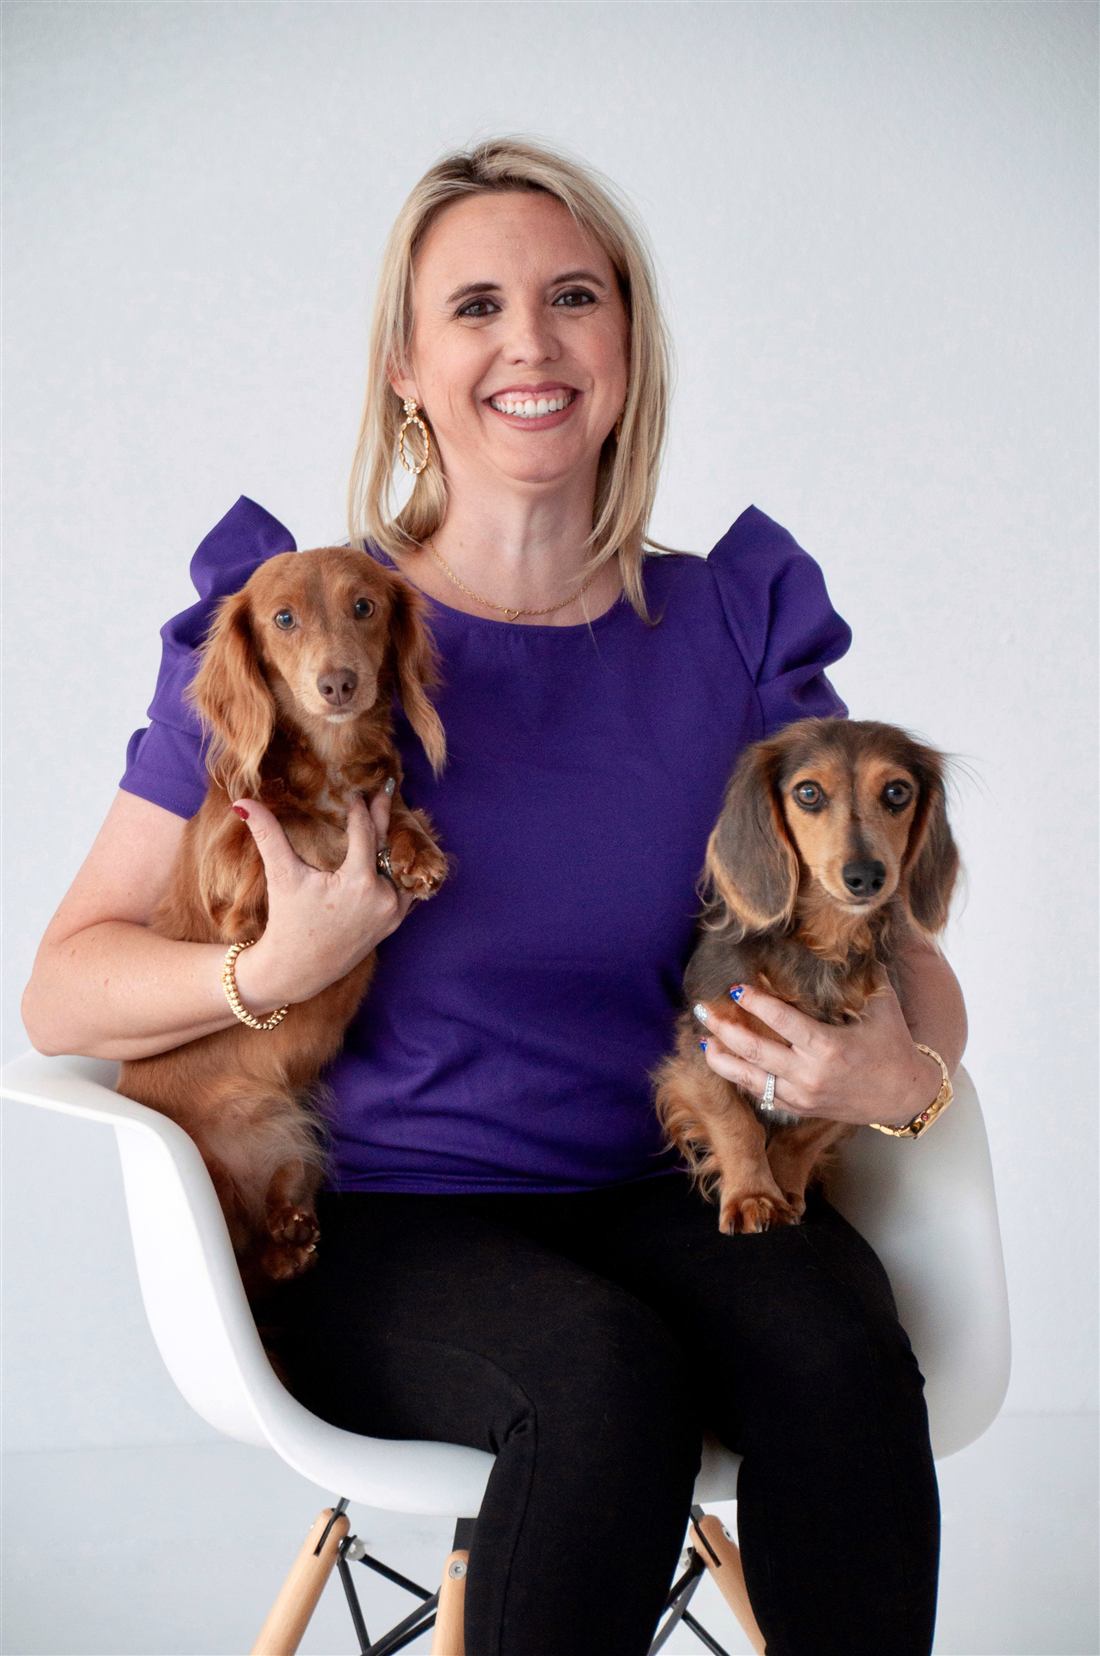
Jax Crider seated with Peanut Butter and Jelly, her dachshund sisters.

Before, during, or after divorce, you deserve a clearer picture of your housing options.

A Divorce Mortgage Planning Consultation is a chance to explore mortgage feasibility, talk through your questions, and understand what information could help you make informed decisions.

You don’t need to have every answer, and scheduling a conversation does not commit you to applying for a loan.

Sources and important context

This guide provides general mortgage education, not legal or tax advice, a loan approval, or a commitment to lend. Financing and servicing options depend on the applicable loan, program, and individual circumstances.